
Florida Consumer Protection Lawyer
Check your situation
Step 1 of 3About a minute. No names or account numbers.
What's going on?
General information, not legal advice. Using this tool does not make you our client.
Credit bureau won't fix it? Collector won't stop? Servicer won't answer?
Newhart Legal, P.A. represents Florida consumers against credit bureaus, debt collectors, mortgage servicers, banks, and card companies that break the law.
Call before you dispute a credit report, write to your servicer, or answer a collector. What you send first, and where you send it, can decide whether the law's protections apply.
Or request a free case review online.
Free consultation · Consumers across Florida · Federal and state court

Credit report errors
Accounts that aren't yours, mixed files, identity theft, and disputes the bureaus ignore. The Fair Credit Reporting Act lets you make them fix it.

Debt collector harassment
Calls that won't stop, calls to your job, threats, and debts you don't owe. Federal and Florida law both let you sue.
Mortgage servicer errors
Misapplied payments, force-placed insurance, escrow mistakes, and letters your servicer ignores.

Unauthorized charges
Federal law limits what you owe for charges and transfers you didn't make and sets deadlines for banks and card companies to investigate.
Before you write anything
What you send first, and where you send it, matters.
Disputing a credit report
A dispute sent through the credit bureau triggers duties you can enforce in court. A dispute sent only to the lender or collector usually does not.
Writing to your servicer
RESPA's response deadlines apply when your letter goes to the address your servicer designates for errors and information requests. The payment address may not count.
Answering a collector
After a collector's first notice, you have about 30 days to dispute in writing and make it stop collecting until it verifies the debt.
Next steps
How it works
1. Tell us what happened
Call, or use the case check above. Talking with us is always free.
2. We review your papers
Credit reports, dispute letters, collection notices, mortgage statements, and anything the company sent you.
3. We act on it
We send the right notice to the right place, or we file suit when the company has broken the law.
About the firm
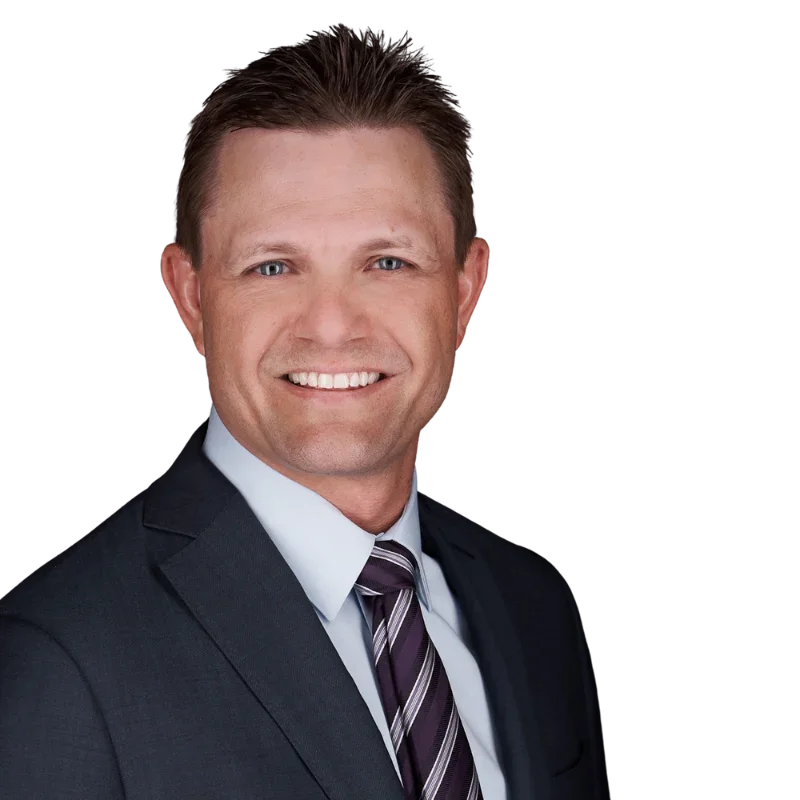
Darren Newhart
Darren Newhart represents Florida consumers in federal and state court against credit bureaus, debt collectors, mortgage servicers, and banks. He was admitted to The Florida Bar in 2015 and practices in the Southern and Middle Districts of Florida and the Eleventh Circuit.
What clients say
“Newhart Legal represented me in a dispute with an apartment complex wrongfully trying to enforce an unsigned lease. I am extremely happy with Mr Newhart's guidance and consul as we worked thru a difficult process. It was a great relief when we finally closed the case in our favor, and Newhart Legal and Darren specifically made a stressful situation as painless as possible. Would highly recommend this firm.”
Turk 22, Google review, June 2025
“With Darren you are in good hands. Highly recommended!”
Spencer Bouhadir, Google review, April 2025
“Attorney Newhart was easy to communicate with, professional and super helpful in successfully bringing my case to resolution. I would definitely recommend.”
Andy B, Google review, August 2024
“With your firm's help and guidance we had a fantastic outcome of our claim. Thank you for a job well done.”
Gerda Mueller-Sheehan, Google review, September 2022
Client reviews describe each client's own experience. You may not obtain the same or similar results.
Questions people ask first
Does it cost anything to talk to you?
No. Every conversation with us is free.
Who pays my lawyer if I win?
If you win, these laws let the court make the company that broke the law pay your attorney's fees and costs: the Fair Credit Reporting Act, the Fair Debt Collection Practices Act, the Real Estate Settlement Procedures Act, the Truth in Lending Act, and the Florida Consumer Collection Practices Act. Fee awards depend on the law, the claim, and the court. Ask us how fees and costs would work in your case.
Should I dispute my credit report myself?
Call before you do. How a dispute is written, and where it goes, decides what the bureau has to do and whether you can sue later.
A collector is calling about a debt I don't owe. What do I do?
Write down who called, when, and what they said. Don't agree to pay until you know the debt is yours. Then call us.
How long do I have to bring a claim?
It depends on the law. Some claims must be filed within one year. Others allow two, three, or five years. Call early so a deadline doesn't decide your case.
Do you handle foreclosures?
No. We don't defend foreclosures. We do sue servicers that mishandle payments, escrow, insurance, fees, and error notices.
Don't send that letter yet.
Call first. Every conversation with us is free.
Prefer to write? Email the firm.